International Tax & Accounting for Investment Funds & Holding Companies — economical, fixed fee

Fixed fees agreed before work starts – 18,000+ clients served

At Legal Quotient Consultants, we help Canadian Investment Funds & Holding Companies streamline finances, reduce stress, and grow with confidence. Economical International Tax & Accounting for Investment Funds & Holding Companies with a fixed fee agreed in writing before any work starts. Call the 24-hour helpline on +1 (416) 619-0068, or request a written quote today.

Fixed-Fee · Trusted · Accurate · Quick · Easy · Economical

In-Depth Tax Trained
CPA Canada (In-Depth Tax Program)
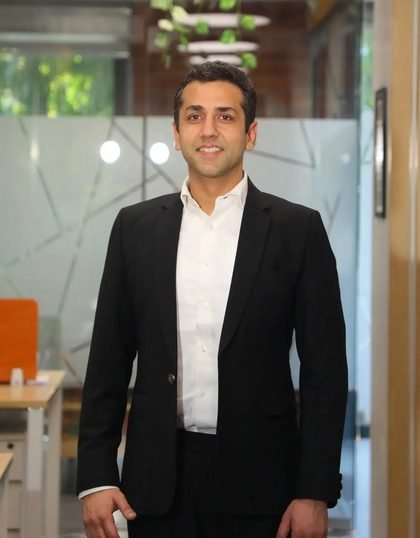
Udit Gupta, founder of Legal Quotient Consultants, at the firm's office
Udit Gupta Cross-Border Tax

Get a fixed quote for your file

Send the details below, or call the 24-hour helpline. We read your documents, put the fee in writing before any work starts.

  • Fixed fee agreed in writing before work starts
  • 15+ years of the founder's cross-border experience
  • 18,000+ clients served across our offices in India, the USA, Canada and the UAE
  • 4 global offices: India, USA, Canada and UAE
24-hour helpline +1 (416) 619-0068

Secure Fixed Quote

Fill details below to lock in pricing and get started today.

Investment Funds & Holding Companies work with Legal Quotient Consultants for the international side of tax: cross-border structuring, Canadian and foreign filings, withholding and treaty relief — fixed fees, one coordinating team.

How Investment Funds & Holding Companies Filing Works

  1. 1
    Share

    Send your documents securely through our portal or by email.

  2. 2
    Prepare

    We prepare your investment funds & holding companies return and every supporting schedule.

  3. 3
    Review

    You review each figure and approve before anything is filed.

  4. 4
    File & pay

    We file with the CRA and send you the confirmation of receipt.

Investment Funds & Holding Companies: Legal Quotient Consultants vs. a Typical Firm

Factor Legal Quotient Consultants Typical Firm
Pricing model Fixed, flat fee Hourly / unpredictable
Experience 15+ years, 18,000+ clients Varies
Helpline 24 hours a day, +1 (416) 619-0068 Office hours only
Where we work Our offices in India, the USA, Canada and the UAE One office only
CRA audit support Included Billed extra

Key Investment Funds & Holding Companies Tax Terms, Defined

T1135
The foreign income verification statement Canadian residents file once specified foreign property passes $100,000 of cost at any time in the year (CRA, 2025 tax year).
Tax Treaty
The bilateral agreement that allocates taxing rights between two countries and relieves double taxation.
Withholding Tax
Tax deducted at source on cross-border payments — Canada's 25% Part XIII rate is often reduced by treaty.
Investment Funds & Holding Companies: Our Analysis

Holding structures live or die on treaty access, beneficial ownership and substance — the MLI's principal-purpose test now sits over every arrangement.

Our engagements pair a Canadian filing position with the foreign one it interacts with, so relief provisions are claimed once, correctly, and with documentation that survives review.

Accounting & Tax Solutions for Investment Funds & Holding Companies

Custom Tax Structures

Read More

Intercompany Cost Allocation

Read More

GST/HST Compliance

Read More

Voluntary Disclosures

Read More

CRA Audit Representation

Read More

Why Investment Funds & Holding Companies Firms Partner with Us

Tailored Tax Planning

Specific deductions, cost allocations, and asset depreciation structures optimized for your niche.

Transparent Fixed Pricing

No surprise bills. Know exactly what you'll pay with our standard, upfront monthly/annual fees.

CRA Compliance & Representation

We back all prepared files. If CRA raises questions, we represent your interest directly.

Stress-Free Process

Through one secure portal, or in person at our offices. Submit documents, review the draft, and we file once you approve it.

Udit Gupta, Chartered Accountant (ICAI) and In-Depth Tax trained

Udit Gupta, Chartered Accountant (ICAI) and In-Depth Tax trained

Founder & Managing Director • In-depth Corporate Tax Specialist

The firm’s founder at his desk in the Delhi office

"A Unique Investment Funds & Holding Companies Approach – Fixed Fee First, Reviewed Before Filing!"

  • Step 1: Share your information – we scope the work on the first call.
  • Step 2: Fixed fee quoted in writing before any work starts.
  • Step 3: We prepare your financials & tax return.
  • Step 4: Review & sign the deliverable before anything is filed.
  • Step 5: We file your return & share final documents.
  • Step 6: The fee was agreed before we started – nothing changes at the end.

Quoted up front, in writing.

Contact Us

Core Investment Funds & Holding Companies Sub-Services & Features

Investment Funds & Holding Companies Cross-Border Billing & Withholding

Tailored compliance, tracking, and tax solutions for Investment Funds & Holding Companies businesses.

Time-billing and practice management tool reconciliation for investment funds & holding companies businesses
Monthly bank, credit card, and operational cash tracking
Accounts Receivable (AR) management and aging reviews
Digital expenses auditing and document collection (Dext) for investment funds & holding companies businesses
CRA Compliance Focus: We review corporate and individual deductions line by line, verify the trial balance in full, and document an audit trail for all Investment Funds & Holding Companies activities.
Investment Funds & Holding Companies Corporate Tax for PC/Holdcos

Tailored compliance, tracking, and tax solutions for Investment Funds & Holding Companies businesses.

T2 Corporate returns for professional & service corporations for investment funds & holding companies businesses
Work-In-Progress (WIP) service billing tax adjustments
Passive investment income holding company tax strategies
CRA audit defense representation and filing protection for investment funds & holding companies businesses
CRA Compliance Focus: We review corporate and individual deductions line by line, verify the trial balance in full, and document an audit trail for all Investment Funds & Holding Companies activities.
Investment Funds & Holding Companies Partner Compensation Planning

Tailored compliance, tracking, and tax solutions for Investment Funds & Holding Companies businesses.

Owner dividend vs salary structuring calculations for investment funds & holding companies businesses
Partner profit-sharing split-ratio allocations
EHT, source deductions, and payroll filings
Custom employee portal for online payslips for investment funds & holding companies businesses
CRA Compliance Focus: We review corporate and individual deductions line by line, verify the trial balance in full, and document an audit trail for all Investment Funds & Holding Companies activities.
Investment Funds & Holding Companies CFO & Growth Advisory

Tailored compliance, tracking, and tax solutions for Investment Funds & Holding Companies businesses.

Service unit economics and billable hour realizations for investment funds & holding companies businesses
Staff utilization and hourly labor efficiency reporting
Cash flow projections for agency/consultancy scaling
Due diligence and valuation reports for mergers for investment funds & holding companies businesses
CRA Compliance Focus: We review corporate and individual deductions line by line, verify the trial balance in full, and document an audit trail for all Investment Funds & Holding Companies activities.
Investment Funds & Holding Companies Cross-Border Reporting

Tailored compliance, tracking, and tax solutions for Investment Funds & Holding Companies businesses.

Foreign property and foreign affiliate statements for investment funds & holding companies businesses
Intercompany charges documented before they are queried
Withholding review on every payment leaving the country
Treaty positions written up with the evidence behind them for investment funds & holding companies businesses
CRA Compliance Focus: We review corporate and individual deductions line by line, verify the trial balance in full, and document an audit trail for all Investment Funds & Holding Companies activities.
Investment Funds & Holding Companies Personal Tax for Partners

Tailored compliance, tracking, and tax solutions for Investment Funds & Holding Companies businesses.

T1 returns for consultants, partners, and practitioners for investment funds & holding companies businesses
Automobile logbook write-offs & home office calculations
Professional licensing and training dues write-offs
Cross-border US/Canada tax return filing services for investment funds & holding companies businesses
CRA Compliance Focus: We review corporate and individual deductions line by line, verify the trial balance in full, and document an audit trail for all Investment Funds & Holding Companies activities.

Cross-border tax for investment funds and holding companies

A fund or holding company earns passive income, and passive income earned abroad is exactly what the anti-deferral regimes target: Canada's foreign accrual property income rules, the United States' controlled-foreign-corporation and passive-foreign-investment-company rules, and their equivalents elsewhere tax the shareholder each year on income the entity has not distributed. Which regime applies turns on who controls the entity, where it is resident and what it does, and a holding company that is efficient for one shareholder can be punitive for another in a different country.

The flows matter as much as the structure. Dividends, interest and capital gains paid up the chain each carry withholding at source and a treaty rate that depends on the recipient's residence and substance; treaty anti-abuse rules deny the rate to entities interposed to obtain it; and the surplus or earnings-and-profits computations at each level decide how a distribution is taxed when it finally reaches an individual. Fund vehicles add investor-level reporting that differs for every country an investor lives in.

  • Classification of each entity under the anti-deferral rules of every shareholder's country, and the annual accrual computations where they apply.
  • Treaty analysis of each distribution in the chain, with the substance the anti-abuse rules require documented.
  • Surplus and earnings computations at each level, and the investor-level statements a fund's foreign investors need.

Our family holding company is in Canada and one shareholder lives in the United States. What changes? The company may be a controlled foreign corporation or a passive foreign investment company for that shareholder, bringing annual US reporting and accrual taxation; the shareholding is often restructured or the company's activities changed to manage it.

Can a holding company in a treaty jurisdiction reduce withholding on dividends from our subsidiaries? Only where it has genuine substance and a business purpose there; the principal-purpose test and limitation-on-benefits articles are written to deny the rate to a company that exists only to hold shares and collect treaty benefits.

Investment Funds & Holding Companies Tax Filing Fixed Pricing

Corporate Tax Filing
$999/One-time filing fee

T2 corporate tax filing, balance sheets, income statements compilation, corporate tax optimization, and direct CRA representation.

Explore Details
Partnership Tax Filing
$800/Partnership return

T5013 partnership information returns, K-1 partner schedule allocations, structural planning, and tax minimization advisory.

Explore Details
Transfer Pricing Documentation
$2,500/Documentation file

Functional analysis, benchmarking study, local file and master file, prepared so the pricing policy stands up to an examination on either side of the border.

Explore Details
Trust-Estate Tax Filing
$799/Trust return

T3 trust tax return filing, testamentary trust setups, estate distribution allocations, and strategic inheritance planning.

Explore Details
US Return Preparation
$449/Return, from

Form 1040 from abroad with the exclusion or the credit, FinCEN 114 and Form 8938 where the tests are met, and the Canadian return reconciled against it.

Explore Details
Catch-Up Filing Package
$349/Year brought current

Unfiled years brought current in the order that works, the disclosure route chosen on the facts, and the earliest year prepared first because it sets the rest.

Explore Details
Personal Tax Filing
$349/Return starting fee

T1 tax returns compilation for students, salaried employees, and self-employed. Covers T4/T5 matching, RRSP credits, and medical deductions.

Explore Details
GST/HST Sales Tax Filing
$400/Filing cycle

Sales tax ledger reconciliation, Input Tax Credits (ITCs) verification, Netfile electronic submission to CRA, and provincial compliance checks.

Explore Details

Begin Your Journey with a Cross-Border Investment Funds & Holding Companies Tax Team

Our Expert Investment Funds & Holding Companies Accounting Firm & Accounting Team

Udit Gupta, International tax, cross-border tax and transfer pricing: USA, Canada, India and UAE at LQ Consultants
Director · International Tax, Cross-Border Tax & Transfer Pricing Expert

CA (India), CA (Malaysia)

Udit Gupta on LinkedIn

Abhinav Gupta, India international tax, cross-border tax and transfer pricing at LQ Consultants
Director · India International Tax, Cross-Border Tax & Transfer Pricing

CA (India)

Abhinav Gupta on LinkedIn

Raghav Gupta, UAE and India international tax, cross-border tax and transfer pricing at LQ Consultants
Director · UAE & India International Tax, Cross-Border Tax & Transfer Pricing

FCA (India)

Raghav Gupta on LinkedIn

Anmol Mittal, USA and Canada international tax, cross-border tax and transfer pricing at LQ Consultants
Director · USA & Canada International Tax, Cross-Border Tax & Transfer Pricing

CPA (Canada), CPA (USA), CA (India)

Anmol Mittal on LinkedIn

Vinayak Indolia, CFO services for Canada and India at LQ Consultants
Director · CFO Services, Canada & India

CPA (Canada), CA (India)

Vinayak Indolia on LinkedIn

Meet Our Entire Team of Experts

Specialized Industries We Serve for Investment Funds & Holding Companies

Healthcare & Medical
Real Estate & Property
Construction & Trades
E-Commerce & Retail
Professional Services
Restaurants & Cafes
Manufacturing & Logistics
Non-Profits & NPOs
Technology & Startups
Healthcare & Medical

Specialized compliance accounting and tax optimization designed for medical clinics, general practitioners, dentists, and pharmacists in Canada.

  • Overhead cost allocation & clinic expense tracking
  • Medical professional corporation (MPC) tax planning
  • GST/HST exemption review and input tax credit claims
  • Full payroll integration for associates and clinic staff
Explore Healthcare Services
Real Estate & Property

Strategic tax planning and custom accounting systems built for real estate agents (PRECs), property managers, developers, and property investors.

  • PREC (Personal Real Estate Corporation) tax structuring
  • Section 216 rental filings and net-basis elections
  • Capital gains tax optimization and deferral strategies
  • GST/HST rebate filings on new residential properties
Explore Real Estate Services
Construction & Trades

Progress billing systems, subcontractor compliance, and job costing models to keep builders, general contractors, and trades compliant and profitable.

  • Project-by-project job costing & margin tracking
  • Subcontractor T5018 slip preparation & filing
  • Work-in-progress (WIP) accounting & bank compliance
  • WSIB and provincial workers' compensation reporting
Explore Construction Services
E-Commerce & Retail

Multi-channel sales tax tracking, inventory accounting integration, and financial analytics for Shopify, Amazon FBA, and WooCommerce businesses.

  • Automated integrations with Shopify, Amazon, Stripe, etc.
  • Multi-province GST/HST/PST sales tax filing
  • Real-time inventory valuation and COGS tracking
  • Cross-border sales tax compliance and duty tracking
Explore E-Commerce Services
Professional Services

Accurate corporate filing, cross-border reporting and assignment payroll for consulting firms, tech startups, legal practices and creative agencies.

  • Time-tracking integrations and utilization reports
  • Shareholder compensation and dividend planning
  • SR&ED tax credit tracking and documentation
  • Withholding review on cross-border invoicing
Explore Professional Services
Restaurants & Cafes

POS integrations, tip tracking, food cost of goods sold (COGS) analytics, and weekly payroll processing built for Canada's food and beverage sector.

  • POS report synchronization & cash flow daily audit
  • Tip pooling calculations & CRA compliance audits
  • Food, beverage, and labor cost variance reports
  • Vendor payment management (Accounts Payable)
Explore Restaurant Services
Manufacturing & Logistics

Cost accounting, raw materials inventory valuation, supply chain overhead tracking, and driver payroll setups for manufacturers and distributors.

  • Bill of materials (BOM) cost tracking & analysis
  • Standard cost audits & variance analysis
  • Multi-warehouse inventory accounting controls
  • Fleet expense monitoring and logbook checks
Explore Manufacturing Services
Non-Profits & NPOs

Cross-border grant and donation relief, foreign-donor receipting questions, and the reporting a charity with activity in two countries carries to maintain status.

  • Fund accounting & grant allocation tracking
  • Cross-border donation and grant relief
  • Foreign-funded programme reporting
  • Board audit assistance & donor report packs
Explore Non-Profit Services
Technology & Startups

High-growth financial management, SR&ED tax credits tracking, Virtual CFO advisory, and venture capital compliance for tech companies across Canada.

  • SR&ED tax credit filing and documentation mapping
  • Monthly cash burn, runway, and financial dashboard metrics
  • Multi-currency conversion and SaaS revenue sourcing
  • Virtual CFO support for fundraising and investor reports
Explore Tech Services

International Tax Help, Wherever You Are

1. Select Country
2. Choose State / Province
Service Location

Cross-Border Tax — Ontario, CA

Corridor work for clients based in Ontario: US and foreign income on both returns, T1135 and 8938 reporting, departure and newcomer years, handled with the Canadian return.

Secure Portal & Video Meetings
+1 (416) 619-0068
Popular services in Ontario:

Investment Funds & Holding Companies Frequently Asked Questions

What tax deductions are investment funds & holding companies businesses most likely to miss?

The recurring ones are capital cost allowance on equipment placed in service late in the year, the business-use portion of vehicle and home-office costs, and professional development. Each is defensible when documented at the time and difficult to defend when reconstructed later.

How much does accounting for investment funds & holding companies businesses cost?

A corporate cross-border filing starts at $999 and transfer-pricing documentation at $2,500, quoted as a fixed fee before work begins. Sector complexity does not add a surcharge. Review the full price list.

Do investment funds & holding companies businesses need to register for GST/HST?

Registration is mandatory once taxable revenue exceeds $30,000 over four consecutive quarters. Registering voluntarily below that threshold is often worthwhile, because it lets you recover input tax credits on startup and equipment purchases.

Should I incorporate my investment funds & holding companies business?

Incorporation usually pays off once profit consistently exceeds what you draw personally, because retained earnings are taxed at the small business rate rather than your marginal rate. Below that point the added compliance cost often outweighs the benefit. We model both before you decide.

What records do investment funds & holding companies businesses need to keep?

The CRA requires six years of books and records from the end of the tax year they relate to: invoices, receipts, bank statements, payroll records and contracts. Digital copies are acceptable provided they are legible and complete.

How do you handle payroll for investment funds & holding companies businesses?

We run the cycle, remit source deductions on schedule, and issue T4s ahead of the February deadline. A late remittance draws a graduated penalty of 3% to 10% depending on how many days late it is. A second or later assessment in the same calendar year can be charged at 20%, but only where the failure was knowing or grossly negligent (CRA, 2025). See our payroll service.

Can you work with my existing accountant and their software?

Yes. Most of these engagements run alongside an existing accountant: they keep the domestic file, we take the cross-border piece, and the boundary is agreed in writing. You are not required to change anythiems to become a client, and we never charge a conversion fee.

What if my investment funds & holding companies business operates in more than one province?

Multi-province operations allocate taxable income by permanent establishment and payroll, and sales tax rules differ by jurisdiction. We handle the allocation schedules and the differing GST, HST, PST and QST obligations in one engagement.

When should an investment funds & holding companies business register for GST/HST?

Registration becomes mandatory once taxable supplies pass $30,000 over four consecutive calendar quarters, and the obligation starts almost immediately rather than at the next year-end. Registering voluntarily below that threshold is often worthwhile when you are buying equipment, because it makes the tax on those purchases recoverable.

How long does the CRA expect an investment funds & holding companies business to keep records?

Six years from the end of the tax year the records relate to. That covers invoices, receipts, bank statements, payroll records and the working papers behind the return. Records supporting the purchase of a capital asset must be kept six years past the year the asset is finally sold.

What happens if an investment funds & holding companies business files late?

The late-filing penalty is 5% of the balance owing plus 1% of that balance for each full month the return is late, to a maximum of 12 months (CRA, 2025 tax year). Where the CRA has issued a demand to file and charged a late-filing penalty in any of the three preceding tax years, the penalty rises to 10% of the balance owing plus 2% for each full month, to a maximum of 20 months (CRA, 2025 tax year). Interest compounds daily from the balance-due date regardless of when the return is filed.

Can an investment funds & holding companies business deduct vehicle costs?

Yes, in proportion to business use, and the logbook is what supports it. The CRA accepts a full-year log, or a three-month sample backed by a complete prior-year log. Travel between home and a regular place of work is personal; travel between work locations is business.

Should an investment funds & holding companies business incorporate?

Incorporation usually pays once profit consistently exceeds what the owner draws personally, because the retained amount is taxed at small business rates rather than personal rates. Where the entire profit is withdrawn each year, incorporation often costs more in filing and compliance than it saves.

What triggers a CRA audit for an investment funds & holding companies business?

Ratios that sit outside sector norms, repeated losses, large or round-numbered expense claims, and mismatches between filed slips and reported income. Most reviews are resolved on documentation alone, which is why contemporaneous records matter more than the size of any single claim.

How are employees and subcontractors treated differently for an investment funds & holding companies business?

The CRA looks at control, ownership of tools, chance of profit and risk of loss rather than what the contract is titled. Where a worker is reclassified as an employee, the unremitted CPP, EI and withholding land on the payer, together with penalties and interest.

What instalments does an investment funds & holding companies business have to pay?

Individuals pay quarterly instalments once net tax owing passes $3,000 — $1,800 for Quebec residents — in the current year and in either of the two preceding years (CRA, 2026). Corporations generally pay monthly, with many small CCPCs eligible for quarterly instalments instead. Basing them on a current-year estimate avoids overpaying after a strong year.

When are tax returns due in Canada for Investment Funds & Holding Companies businesses?

For corporations in the investment funds & holding companies sector, T2 tax filings are due within 6 months of the fiscal year-end. Personal returns for sole proprietors are due June 15, with balances payable by April 30.

What tax deductions are available for Investment Funds & Holding Companies companies?

Common write-offs include operating expenses, inventory costs, technology software licenses, marketing, employee wages, home workspace allocation, and capital assets depreciation.

Why choose Legal Quotient Consultants for Investment Funds & Holding Companies accounting?

We provide specialized cross-border compliance, corporate filing, and treaty planning on fixed fees agreed in writing before work starts.

Why are corporations double taxed?

Corporate double taxation happens because the company and its owners are separate taxpayers. The company pays tax on its profit; when the after-tax profit is distributed, the shareholder pays tax on the dividend. Canada softens this with the dividend gross-up and credit, which is meant to leave a shareholder roughly where they would have been earning the income directly. The United States taxes the C corporation and then the dividend, with no equivalent integration. See dividends to a foreign parent.

Which business structure has double taxation?

The corporation — specifically a US C corporation, where profit is taxed to the company and the dividend again to the shareholder. Sole proprietorships, partnerships and LLCs treated as flow-throughs are taxed once, in the owners' hands. Across borders that tidy answer breaks: an entity treated as a flow-through in one country can be opaque in the other, which produces a mismatch neither system planned for. See LLC against corporation for Canadians.

Still have questions? View our FAQ page or contact us.

24-Hour Helpline: +1 (416) 619-0068

Ready to get started with Investment Funds & Holding Companies?

Talk to a professional tax accountant about your situation. No obligation, and the fee is agreed in writing before any work starts.

  • Tax accountant led team
  • Fixed fees, no hourly billing
  • 18,000+ clients served

What these engagements turn on

Case study 1

Rebuilding the earnings history of a dormant foreign subsidiary

A holding company wanted to bring cash home from a subsidiary abroad that had been left alone for years. Nobody had tracked which of the subsidiary's earnings had already borne foreign tax and which had not, and the Canadian treatment of a dividend turns on exactly that history. We worked back through the subsidiary's statutory accounts and local filings, rebuilt the pools year by year, and set out in a memorandum which part of a distribution would be taxable on receipt and which would not. The dividend was then declared with the analysis on file.

Case study 2

Putting a withholding control in front of every investor distribution

A fund had been paying quarterly distributions to investors in several countries and applying treaty rates from a spreadsheet nobody owned. Residence declarations were missing for part of the register, and some on file had lapsed. We rebuilt the register against the subscription documents, wrote to investors for current declarations, and set a rule that no payment runs until the declaration supporting its rate is in the file. Where past payments had been under-withheld, we quantified the exposure and corrected it with the CRA before the next distribution went out.

Case study 3

Corporate residence reviewed after the sole director moved abroad

The only director of a family holding company relocated permanently, and board decisions began to be taken from the new country. Residence for tax follows where the company is actually managed, not where it was incorporated, so the move put the company's status in question along with its treaty position. We reviewed the minute books, banking authorities and the pattern of decision-making, explained what would need to change for the company to remain resident where the family intended, and documented the arrangements that were then put in place.

Case study 4

Documenting whether an investment company held capital or traded

A holding company had reported its share disposals as capital gains for several years while the turnover in the portfolio was rising. No memorandum existed explaining why that treatment was right, and an audit would have started with that gap. We reviewed holding periods, the source of the funding, the instructions given to the manager and the original purpose recorded when positions were bought, then wrote the position up with the supporting records attached. The client now has a file that answers the question on the day it is asked.

Case study 5

Testing treaty relief before a payment left through an intermediate entity

A group planned to route a distribution through an entity in a third country that carried a favourable treaty rate. The entity had no staff, no local decision-making and an obligation to pass the money on almost immediately. We set out why relief at that level would be hard to defend, what the Canadian payer's own liability would be if the rate were denied, and what a defensible structure would need to look like. The group changed the payment path rather than rely on a position it could not support.

Case study 6

Catching up years of unreported foreign holdings for a family group

A family holding company discovered that accounts and share positions held outside Canada had never been included in its annual information reporting, although the returns themselves had always been filed. The exposure here attaches to the failure to report rather than to tax owing. We built an inventory of every foreign account, loan and shareholding across the years in question, prepared the outstanding reporting, and made the disclosure to the CRA. An annual refresh of the inventory now runs alongside the year-end file.

Case study 7

A TFSA That Costs More Than It Saves

Canadian tax-free accounts are not tax-free to a US person, and some of them carry a reporting form of their own. The file is a review of what is held, what each account triggers on the US side, and whether the account is worth keeping once the reporting is priced in.

Read how this one runs
Case study 8

Selling Into the US Without an Entity, and Filing in Several States

State obligations are set by each state, and a treaty does not reach them. The review measures activity against each state's own thresholds and separates the states where registration is required from the ones where it is not.

Read how this one runs

All case studies — every published engagement in one place.

Our practitioners are alumni of leading accounting and tax institutions

Where our partners studied — CPA Canada (In-Depth Tax Program), AICPA, the Institute of Chartered Accountants of India and the Malaysian Institute of Accountants.

Request a Quote +1 (416) 619-0068








