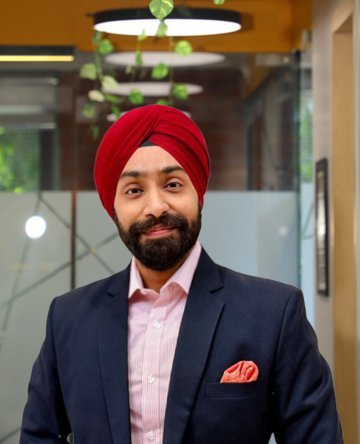
Senior Consultant · Canada Tax · Legal Quotient Consultants
Canadian tax, read by someone qualified in two countries
CPA (Canada), FCA (India)
Gurjot Singh works on Canada tax at Legal Quotient Consultants. He holds the two designations above, one Canadian and one Indian, and the Indian one at fellowship level.
Canadian files with an Indian side to them are a large share of this practice's work: a family that moved and kept property or investments behind, or a business with a related company in India. Reading both sides is what stops income being taxed twice or reported once.
- Canada tax
- Canada and India qualified
Areas of expertise
Canadian personal tax
T1 returns for residents, newcomers and people leaving Canada.
Canadian corporate tax
T2 returns and the statements behind them.
Canada and India
Qualified in both countries, for files with an Indian side to them.
Qualifications
Canadian professional accounting designation
Qualified through the Canadian accounting profession's national certification programme and admitted to membership by a provincial regulatory body.
Fellow Chartered Accountant (India)
Fellow member of The Institute of Chartered Accountants of India (ICAI) — the senior grade of membership of India's statutory body for chartered accountants.
What Gurjot handles
Canadian personal returns
T1 returns for residents and newcomers, including the year someone becomes resident.
Canadian business returns
T2 returns and the financial statements behind them.
Foreign property reporting
the T1135 and the related foreign income a Canadian return has to include.
Foreign tax credits
tax already paid in India or elsewhere, credited in Canada once and correctly.
Who Gurjot works with
Newcomers to Canada
The first-year return, the date residence began, and the foreign property that has to be reported from then on.
Families with ties abroad
Property, investments or income left behind in India or elsewhere, reported and credited correctly in Canada.
Owner-managed companies
Small Canadian corporations whose owners want the books, the return and their own pay planned together.
Disclosures
Professional status. The designations on this page are Gurjot Singh's own, held personally. Legal Quotient Consultants is not a licensed public accounting firm in Ontario, and nothing here says otherwise.
Scope. This practice prepares and files tax returns and supporting documentation, and represents clients with the revenue authorities. It does not perform audit or assurance engagements.
General information. Nothing on this page is advice for a particular situation. Book a consultation and the position is worked out on the facts of your file, with the fee agreed in writing before any work starts. Call +1 (416) 619-0068.
Profile last reviewed September 2026.
Cross-border tax case studies
Wintering in the US Long Enough to Become a US Filer
Days in the United States accumulate across three years, and enough of them make you a US resident for tax regardless of immigration status. The file counts the days properly and files the statement that keeps the position closer connection rather than residence.
Read how this one runsTen Years of Missed Returns Filed as One Engagement
Filing many years at once is a sequencing problem: carry-forwards, instalments and credits from the earliest year feed the latest. Filing them out of order is what turns a recoverable position into an assessed one.
Read how this one runsLeaving Canada — the Bill You Get for Assets You Still Own
Emigrating triggers a deemed disposition of most holdings, which produces tax on gains never realised in cash. The file values the property, identifies what is excluded, and looks at whether security can be posted rather than the tax paid outright.
Read how this one runsA Home Kept in Canada After the Move Abroad
A dwelling left available is the tie the CRA weighs most heavily, and its treatment differs depending on whether it is rented at arm's length. The file settles the residence position first and the rental reporting second.
Read how this one runsA Family Trust Abroad With Reporting on Both Sides
A trust settled in one country and a beneficiary living in another produces reporting for the trust, the settlor and the beneficiary, on different forms and different dates. The engagement maps who files what before anything is prepared.
Read how this one runsInterest and Penalties Put to a Relief Application
Relief is discretionary and is decided on the circumstances that caused the delay, evidenced year by year. The application is built from the same chronology the filings rest on, so the two cannot contradict each other.
Read how this one runsPaid for Work Done in Canada While Living Elsewhere
Employment carried out in Canada is taxable here even where the employer and the bank account are not. The engagement establishes how many of the days were worked in Canada, applies the treaty employment article, and deals with the withholding the payer has already taken.
Read how this one runsA Non-Resident Estate Holding US Assets
US situs assets sit inside the US estate tax net regardless of where the owner lived, and the exemption available to a non-resident is not the resident one. The file establishes situs asset by asset before any relief is claimed.
Read how this one runsAll case studies — every published engagement in one place.
Core International & Cross-Border Tax Services
Strategy and compliance for income, assets and families spread across borders.
Industries & Client Types We Serve Worldwide
Cross-border tax for sellers shipping worldwide: marketplace withholding, foreign registrations and inventory nexus handled before they become audits.
Marketplaces withhold, remit and report in their own right, so the tax position of a single sale is decided by where the stock sat, where the buyer was and which platform collected — not by where the company is registered. We reconcile the platform's own filings against the returns before either is submitted.
- Foreign VAT / GST / sales tax registrations
- Marketplace withholding reviews
- Inventory nexus & PE analysis
- Multi-currency books reconciled
- Cross-border revenue sourcing & withholding
- IP structuring with real substance
- Equity for cross-border teams
- U.S. expansion: entity & PE setup
- Reg 105 / 102 waivers
- Permanent establishment risk
- Partner mobility planning
- Cross-border withholding recovery
- Section 216 rental returns
- FIRPTA withholding recovery
- Section 116 clearance
- Treaty credit optimization
- Transfer pricing documentation (s.247)
- Customs value vs transfer price
- Foreign affiliate reporting (T1134)
- Country-by-country reporting
- Reg 105 & U.S. CWA agreements
- Multi-state & country calendars
- Touring income allocation
- Royalty & image-rights withholding
- Residency analysis before moving
- Employer payroll exposure
- Totalization & social security
- Foreign tax credits
- Treaty access & PPT reviews
- FAPI & surplus computations
- Withholding-efficient routing
- Governance & substance