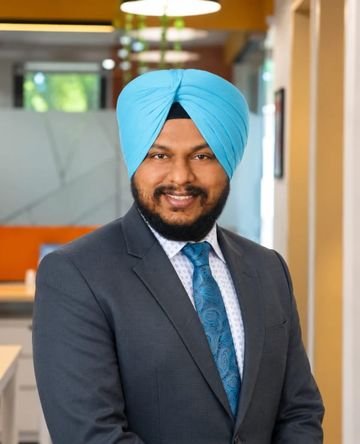
Senior Consultant · Corporate Accounting & Financial Reporting · Legal Quotient Consultants
Corporate accounting, from the ledger to the return
CPA (Canada), CA (India)
Gurpreet Singh is a Senior Consultant at Legal Quotient Consultants, based in Toronto. He holds the two designations above, one Canadian and one Indian, and trained as a chartered accountant with The Institute of Chartered Accountants of India from 2005 to 2010.
His background is corporate accounting at a senior level in banking. A tax return is only as reliable as the accounts underneath it, and that is his part of a file: the year-end close, the reconciliations and the financial statements, prepared so the return built on them holds up when it is reviewed, in Canada or in the second country a cross-border group reports in.
- Toronto
- Corporate accounting
- Canada and India qualified
Direct: +1 (647) 355-1987 · gurpreet@lqconsultants.com
Areas of expertise
Corporate accounting
The month-end and year-end close, the reconciliations and the entries behind them.
Financial reporting
Financial statements a lender, a shareholder or a revenue authority can rely on.
Canada and India
Qualified in both countries, for groups with a related company on the other side.
Qualifications
Canadian professional accounting designation
Qualified through the Canadian accounting profession's national certification programme and admitted to membership by a provincial regulatory body.
Chartered Accountant (India)
Member of The Institute of Chartered Accountants of India (ICAI), the statutory body that regulates the chartered accountancy profession in India. Membership follows the Institute's examinations and a period of practical training.
The Institute of Chartered Accountants of India, 2005–2010
Chartered accountancy studies and training with India's statutory body for the profession.
What Gurpreet handles
Year-end close
The reconciliations, accruals and adjusting entries that turn a year of transactions into accounts that can be signed off.
Financial statements
Statements prepared from the closed ledger, in the form the business reports in.
The accounts behind the return
The figures a corporate tax return is built on, checked before the return is prepared rather than after.
Intercompany balances
Amounts owed between related companies in different countries, agreed on both sides before either set of accounts closes.
Who Gurpreet works with
Owner-managed companies
Corporations whose owners want the books, the statements and the return to agree.
Cross-border groups
A Canadian company with a related business in India, the USA or the UAE, whose two sets of accounts have to match.
Companies with a lender or investor
Businesses whose financial statements are read by a bank or a shareholder as well as by the tax authority.
Disclosures
Professional status. The designations on this page are Gurpreet Singh's own, held personally. Legal Quotient Consultants is not a licensed public accounting firm in Ontario, and nothing here says otherwise.
Scope. This practice prepares and files tax returns and supporting documentation, and represents clients with the revenue authorities. It does not perform audit or assurance engagements.
General information. Nothing on this page is advice for a particular situation. Book a consultation and the position is worked out on the facts of your file, with the fee agreed in writing before any work starts. Call +1 (416) 619-0068.
Profile last reviewed September 2026.
Files that look like this one
One Salesperson Abroad, and a Corporate Filing Obligation
A single employee with authority to conclude contracts can create a taxable presence for the whole company. The review tests what the person actually does against the treaty article, and where a presence exists, works out what profit is attributable to it.
Read how this one runsA Taxable Presence Created Without an Office
A dependent agent habitually concluding contracts can create a permanent establishment where there is no premises at all. The review tests what the person actually does against what the treaty describes.
Read how this one runsA Company That Needed a Resident on Its Board
Several jurisdictions require a locally resident director before a company can be registered or keep its filings current. The requirement is structural and is settled at incorporation rather than discovered at the first annual return.
Read how this one runsWhether Documentation Was Required At All
The obligation turns on the transactions that actually happened rather than on the size of the group, and the penalty for contemporaneous documentation is charged by reference to the adjustment. The review establishes which side of the line the company sits.
Read how this one runsPaying a Dividend Up to a Foreign Parent
The withholding rate depends on the treaty, on the size of the holding, and on whether the parent is the beneficial owner rather than a conduit. Establishing all three before the payment is what secures the lower rate at source.
Read how this one runsLeaving Canada — the Bill You Get for Assets You Still Own
Emigrating triggers a deemed disposition of most holdings, which produces tax on gains never realised in cash. The file values the property, identifies what is excluded, and looks at whether security can be posted rather than the tax paid outright.
Read how this one runsTax Deducted When Buying From an NRI
Withholding on a sale by a non-resident is applied to the sale value rather than to the gain, so it routinely exceeds the tax due. A lower-deduction certificate obtained before completion avoids locking the difference up.
Read how this one runsFirst Canadian Return After Arriving Mid-Year
The arrival date splits the year and sets the cost base of what you brought with you. Getting that date and those values right is what determines whether a later sale is taxed on the whole gain or only on the part that accrued after landing.
Read how this one runsAll case studies — every published engagement in one place.
Core International & Cross-Border Tax Services
Strategy and compliance for income, assets and families spread across borders.
Industries & Client Types We Serve Worldwide
- Foreign VAT / GST / sales tax registrations
- Marketplace withholding reviews
- Inventory nexus & PE analysis
- Multi-currency books reconciled
Software revenue crosses borders by default — sourcing rules, withholding on licence-like payments and IP location decide the effective rate.
Software revenue is rarely taxed where the team sits. Licence, subscription and service income are characterised differently by each side, and the answer decides withholding at source, treaty relief and whether a foreign customer creates a taxable presence at all — questions that are cheap to settle before the contract and expensive afterwards.
- Cross-border revenue sourcing & withholding
- IP structuring with real substance
- Equity for cross-border teams
- U.S. expansion: entity & PE setup
- Reg 105 / 102 waivers
- Permanent establishment risk
- Partner mobility planning
- Cross-border withholding recovery
- Section 216 rental returns
- FIRPTA withholding recovery
- Section 116 clearance
- Treaty credit optimization
- Transfer pricing documentation (s.247)
- Customs value vs transfer price
- Foreign affiliate reporting (T1134)
- Country-by-country reporting
- Reg 105 & U.S. CWA agreements
- Multi-state & country calendars
- Touring income allocation
- Royalty & image-rights withholding
- Residency analysis before moving
- Employer payroll exposure
- Totalization & social security
- Foreign tax credits
- Treaty access & PPT reviews
- FAPI & surplus computations
- Withholding-efficient routing
- Governance & substance