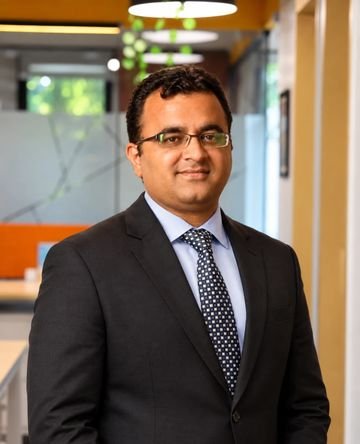
Director · Canada & India Services · Legal Quotient Consultants
Twenty-five years of running the finance function
CA (India)
Rabel Advani looks after Canada and India based services at Legal Quotient Consultants, from Brampton, Ontario. He is a Chartered Accountant (India) with more than 25 years in financial operations and planning, due diligence and team management.
For eighteen years he was CFO and Director of Spatial Access, a company that became a Deloitte business: he was promoted to CFO within two years of joining, led the sale of the company's entire equity to Deloitte India, and managed the takeover that followed.
- Brampton, Ontario
- Canada and India
- 25+ years in finance
Qualifications
Chartered Accountant (India)
Member of The Institute of Chartered Accountants of India (ICAI), the statutory body that regulates the chartered accountancy profession in India. Membership follows the Institute's examinations and a period of practical training.
Experience
- CFO and Director, Spatial Access (2003–2021) — promoted to CFO within two years; led the sale of the company's entire equity stake to Deloitte India and managed the takeover process.
- Due diligence and deal work — the finance side of a sale from the seller's chair, which is the view a buyer's diligence team tests.
What Rabel handles
Canada and India based services
clients with a business, family or investments in both countries, and the finance and tax questions that come with them.
Financial planning
budgets, forecasts and the planning a business needs before it expands into the second country.
Accounting and financial operations
the processes that produce reliable monthly numbers.
Transaction readiness
getting the books and the documents into the shape a buyer, an investor or a lender will ask for.
Who Rabel works with
Families across Canada and India
Households with income, property or a business in both countries.
Businesses expanding between the two
Companies opening their second operation, in Canada or in India.
Owners preparing for a sale or investment
Businesses getting their books and documents ready for a buyer’s or investor’s diligence.
Disclosures
Professional status. The designations on this page are Rabel Advani's own, held personally. Legal Quotient Consultants is not a licensed public accounting firm in Ontario, and nothing here says otherwise.
Scope. This practice prepares and files tax returns and supporting documentation, and represents clients with the revenue authorities. It does not perform audit or assurance engagements.
General information. Nothing on this page is advice for a particular situation. Book a consultation and the position is worked out on the facts of your file, with the fee agreed in writing before any work starts. Call +1 (416) 619-0068.
Profile last reviewed September 2026.
Cross-border tax case studies
A Second Opinion on a Return Already Filed
A cross-border return prepared on one side only is usually right in isolation and wrong in combination. The review checks residence, source and relief in that order, and says plainly whether an amendment is worth making.
Read how this one runsThe Year of Leaving India
The departure year carries a transition status with its own treatment of foreign income, and the position for the following years follows from how it is set. Getting the first year right saves arguing about the rest.
Read how this one runsIndian Rent Collected While Resident Somewhere Else
Rent from Indian property is taxed in India and again where you live, with relief on one side only. The file gets the Indian deduction right first, then claims the credit on the home return against what was actually paid.
Read how this one runsA Trust Abroad With a Canadian Connection
Contributions or beneficiaries in Canada can bring a foreign trust inside the Canadian net entirely. The analysis is who contributed what and when, because the answer decides whether the trust files here at all.
Read how this one runsA Canadian Working in the US on a Work Visa
Immigration status and tax residence are different tests, and a visa says nothing about which country taxes the salary. The file fixes residence, applies the employment article, and sequences the two returns so the credit lands where it is usable.
Read how this one runsA US LLC Owned From Canada
The two countries classify the vehicle differently, so relief that ought to apply frequently does not and the same profit can be taxed in both hands. The engagement examines whether the structure can be changed and what the change itself costs.
Read how this one runsDeduction at Source on Deposit Interest, Recovered
Where the treaty rate is lower than what was deducted, the difference comes back through a return rather than at source. The file establishes entitlement and files for the years still open.
Read how this one runsResidency Changed Mid-Year and Both Returns Assumed a Full One
A move part-way through a year produces two part-year positions, not two full ones. The engagement establishes the date residence actually changed, allocates income either side of it, and amends whichever return was filed on the wrong footing.
Read how this one runsAll case studies — every published engagement in one place.
Core International & Cross-Border Tax Services
Strategy and compliance for income, assets and families spread across borders.
Industries & Client Types We Serve Worldwide
- Foreign VAT / GST / sales tax registrations
- Marketplace withholding reviews
- Inventory nexus & PE analysis
- Multi-currency books reconciled
- Cross-border revenue sourcing & withholding
- IP structuring with real substance
- Equity for cross-border teams
- U.S. expansion: entity & PE setup
Firms and partners working across borders meet Regulation 105 withholding, PE risk on long engagements and per-country payroll for travelling staff.
A partnership is taxed in the hands of its partners, so one engagement abroad can reach every partner's personal return. The order matters: the waiver is applied for before the invoice, the presence is tracked before it becomes an establishment, and the payroll is registered before the first day worked in the other country.
- Reg 105 / 102 waivers
- Permanent establishment risk
- Partner mobility planning
- Cross-border withholding recovery
- Section 216 rental returns
- FIRPTA withholding recovery
- Section 116 clearance
- Treaty credit optimization
- Transfer pricing documentation (s.247)
- Customs value vs transfer price
- Foreign affiliate reporting (T1134)
- Country-by-country reporting
- Reg 105 & U.S. CWA agreements
- Multi-state & country calendars
- Touring income allocation
- Royalty & image-rights withholding
- Residency analysis before moving
- Employer payroll exposure
- Totalization & social security
- Foreign tax credits
- Treaty access & PPT reviews
- FAPI & surplus computations
- Withholding-efficient routing
- Governance & substance