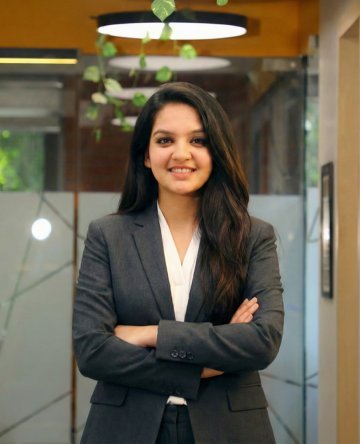
Client Coordination & Client Relations · Legal Quotient Consultants
The person who keeps your file moving
Radhika Singal looks after client coordination and client relations at Legal Quotient Consultants. A cross-border file has a lot of moving parts — documents from two countries, deadlines in both, and more than one person on the team working on it — and someone has to keep them in order.
She is that person for many of our clients: the one who confirms what is needed, chases what is missing, and makes sure you know where your file stands without having to ask.
- Client coordination
- Client relations
Areas of expertise
Client coordination
Documents, deadlines and scheduling across the team.
Client relations
A single point of contact from first call to filed return.
What Radhika handles
Onboarding
the engagement letter, the agreed fee, and the list of documents your file needs.
Document collection
what has arrived, what is missing, and a reminder before a deadline rather than after it.
Scheduling
calls with the practitioner reviewing your file, at a time that works across time zones.
Updates
where your file stands, from first call to filed return.
Who Radhika works with
Every client of the practice
From the first call, until the return is filed.
Clients in different time zones
Calls scheduled across India, the USA, Canada and the UAE.
Disclosures
Scope. This practice prepares and files tax returns and supporting documentation, and represents clients with the revenue authorities. It does not perform audit or assurance engagements.
General information. Nothing on this page is advice for a particular situation. Book a consultation and the position is worked out on the facts of your file, with the fee agreed in writing before any work starts. Call +1 (416) 619-0068.
Profile last reviewed September 2026.
Files that look like this one
Withholding Reduced by the Right Article
Dividends, interest and royalties each have their own article and their own rate, and the payer applies whichever it is satisfied of. Establishing entitlement before payment is what secures the lower rate at source.
Read how this one runsA Pension Taxed Where the Treaty Did Not Intend
Pension and annuity articles allocate taxing rights differently from employment income, and a flat withholding often exceeds what a return would produce. The alternative filing is elective and has a deadline.
Read how this one runsFifteen Per Cent Held Back From a Fee for Services in Canada
A payer must withhold from fees paid to a non-resident for services rendered in Canada, whether or not any tax is ultimately owed. A waiver applied for before the work is invoiced avoids the withholding; after it, the money comes back through a return.
Read how this one runsGetting Sale Proceeds Out of India
Repatriation runs on certification from an accountant and on the account the funds sit in, and the banking rules and the tax rules are separate gates. Both are cleared in sequence rather than together.
Read how this one runsA US LLC Owned From Canada
The two countries classify the vehicle differently, so relief that ought to apply frequently does not and the same profit can be taxed in both hands. The engagement examines whether the structure can be changed and what the change itself costs.
Read how this one runsInformation Returns Missed Behind a Correct Return
The heaviest exposure on a cross-border file is often a disclosure form rather than the tax. Where the return itself was right, the procedures for late information returns turn on a reasonable-cause narrative with dates and documents behind it.
Read how this one runsTen Years of Missed Returns Filed as One Engagement
Filing many years at once is a sequencing problem: carry-forwards, instalments and credits from the earliest year feed the latest. Filing them out of order is what turns a recoverable position into an assessed one.
Read how this one runsA Group File That Had to Describe the Whole Group
The master file is a picture of the business rather than of one company, and it has to agree with what each local file says. Assembling it surfaces inconsistencies between entities that nobody had compared.
Read how this one runsAll case studies — every published engagement in one place.
Core International & Cross-Border Tax Services
Strategy and compliance for income, assets and families spread across borders.
Industries & Client Types We Serve Worldwide
- Foreign VAT / GST / sales tax registrations
- Marketplace withholding reviews
- Inventory nexus & PE analysis
- Multi-currency books reconciled
- Cross-border revenue sourcing & withholding
- IP structuring with real substance
- Equity for cross-border teams
- U.S. expansion: entity & PE setup
Firms and partners working across borders meet Regulation 105 withholding, PE risk on long engagements and per-country payroll for travelling staff.
A partnership is taxed in the hands of its partners, so one engagement abroad can reach every partner's personal return. The order matters: the waiver is applied for before the invoice, the presence is tracked before it becomes an establishment, and the payroll is registered before the first day worked in the other country.
- Reg 105 / 102 waivers
- Permanent establishment risk
- Partner mobility planning
- Cross-border withholding recovery
- Section 216 rental returns
- FIRPTA withholding recovery
- Section 116 clearance
- Treaty credit optimization
- Transfer pricing documentation (s.247)
- Customs value vs transfer price
- Foreign affiliate reporting (T1134)
- Country-by-country reporting
- Reg 105 & U.S. CWA agreements
- Multi-state & country calendars
- Touring income allocation
- Royalty & image-rights withholding
- Residency analysis before moving
- Employer payroll exposure
- Totalization & social security
- Foreign tax credits
- Treaty access & PPT reviews
- FAPI & surplus computations
- Withholding-efficient routing
- Governance & substance