Cross-Border Tax Accountants in Punjab — cost-effective, fixed fee

Fixed fees agreed before work starts – 18,000+ clients served

We plan and file cross-border taxes for individuals, corporations and trusts in Punjab — U.S. and Canadian returns, expat and non-resident filings, treaty relief and foreign reporting, at fixed fees agreed in writing. Ask us about cost-effective Cross-Border Tax Accountants in Punjab: call the 24-hour helpline on +1 (416) 619-0068, or request a written fixed quote today.

Fixed-Fee · Trusted · Accurate · Quick · Easy · Economical

In-Depth Tax Trained
CPA Canada (In-Depth Tax Program)
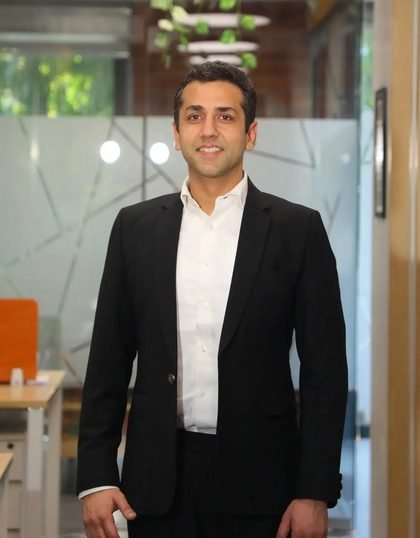
Udit Gupta, founder of Legal Quotient Consultants, at the firm's office
Udit Gupta Cross-Border Tax

Fixed Fees for Clients in Punjab

These are our own fixed fees, in US dollars, for the cross-border work we do for you — agreed in writing before work starts. They are not a price for filing under Punjab's own tax system, and they do not change with where you live.

See the full fee list

Cross-border and international tax for Punjab, India: Legal Quotient Consultants serves clients in Punjab remotely from Toronto — international tax planning, expat and non-resident filings, U.S. and Canadian returns, transfer pricing and treaty relief, at fixed fees.

How Punjab Filing Works

  1. 1
    Share

    Send your documents securely through our portal or by email.

  2. 2
    Prepare

    We prepare your punjab return and every supporting schedule.

  3. 3
    Review

    You review each figure and approve before anything is filed.

  4. 4
    File & pay

    We file with the tax authority the return belongs to and send you the confirmation of receipt.

Punjab: Legal Quotient Consultants vs. a Typical Firm

Factor Legal Quotient Consultants Typical Firm
Pricing model Fixed, flat fee Hourly / unpredictable
Experience 15+ years, 18,000+ clients Varies
Helpline 24 hours a day, +1 (416) 619-0068 Office hours only
Where we work Our offices in India, the USA, Canada and the UAE One office only
CRA audit support Included Billed extra

Key Canadian Tax Terms for Clients in Punjab

T1135
The foreign income verification statement Canadian residents file once specified foreign property passes $100,000 of cost at any time in the year (CRA, 2025 tax year).
Tax Treaty
The bilateral agreement that allocates taxing rights between two countries and relieves double taxation.
Withholding Tax
Tax deducted at source on cross-border payments — Canada's 25% Part XIII rate is often reduced by treaty.
Punjab: Our Analysis

The Canada–India DTAA, NRI account income (NRE/NRO), Indian capital gains regimes and TDS withholding recovery anchor a large share of our client base.

For clients in Punjab, engagements run through a secure portal with scheduled video reviews — the same specialist team and the same fixed fee wherever you are. Typical files pair local income and assets with Canadian filings or vice versa, sequenced so treaty relief and foreign tax credits are claimed once and correctly.

Cross-border tax in Punjab: what is different here

Punjab levies a development tax on income earners — its form of profession tax — and stamp duty on property, alongside the national income tax. Its distinguishing feature for this practice is the diaspora: Punjab has one of the largest overseas populations of any Indian state, concentrated in Brampton, Surrey, Vancouver and Calgary, so a Punjab file is almost always a Canada file as well.

Agricultural land is the recurring subject. Non-resident Indians may inherit farmland but generally may not buy it, and the sale of inherited land raises the question of whether the gain is taxable in India at all and how the proceeds may be repatriated. Around it sit the ordinary NRI questions — NRE and NRO accounts, rent from Ludhiana and Jalandhar property paid to owners in Canada, tax deducted at source on sales, and gifts between parents in Punjab and children in Ontario or British Columbia.

  • Canadian families of Punjabi origin inheriting or selling farmland in Punjab and the ownership, taxability and repatriation rules.
  • Rent and sale proceeds from Ludhiana, Jalandhar and Chandigarh property paid to owners in Brampton, Surrey and Calgary.
  • Gifts and remittances between parents in Punjab and children in Canada, and the reporting each side expects.

Can a Canadian of Indian origin buy agricultural land in Punjab? Generally no. Non-resident Indians and overseas citizens may inherit farmland but are restricted from buying it; inherited land may be sold to a resident Indian, with tax and repatriation rules applying to the proceeds.

Is a gift from my parents in Punjab taxable in Canada? Canada does not tax gifts received, but the funds' arrival, the account they come through and any income they later earn are reported; India applies its own rules on gifts to relatives and on the outward remittance.

Why Choose Legal Quotient Consultants in Punjab?

Expert Punjab Tax Filing & Planning

Providing tailored Punjab tax filing and planning to reduce liabilities, maximize refunds, and ensure compliance in every jurisdiction that taxes the file.

Fixed Fees, Agreed Before We Start

Punjab filing quoted as a fixed fee before work begins, with no hidden extras — the number you are quoted is the number you are billed.

Compliance & Cross Border Tax

From information returns to corporate audits, protect your Punjab business with compliance in every jurisdiction that taxes the file and expert cross border tax strategies.

A Secure Engagement

Documents, questions and signatures move through one secure portal, so a Punjab file runs the same from Toronto, Dubai or Delhi.

Two of the firm’s advisers and the team in the open-plan office
Secure Fixed Quote

Fill details below to lock in pricing and get started today.

"A Unique Punjab Approach – Fixed Fee First, Reviewed Before Filing!"

  • Step 1: Share your information – we scope the work on the first call.
  • Step 2: Fixed fee quoted in writing before any work starts.
  • Step 3: We prepare your financials & tax return.
  • Step 4: Review & sign the deliverable before anything is filed.
  • Step 5: We file your return & share final documents.
  • Step 6: The fee was agreed before we started – nothing changes at the end.

Quoted up front, in writing.

Contact Us

Core International & Cross-Border Tax Services

International Tax Planning & Advisory

Strategy and compliance for income, assets and families spread across borders.

One coordinating team: filings on every side of the border are sequenced so treaty relief and foreign tax credits are claimed once — and in the right country.
U.S. & Cross-Border Tax Returns

Both systems, one desk — 1040s and T1s planned together, not in isolation.

Dual filers: U.S. citizens in Canada and Canadians with U.S. income run two parallel systems — we prepare both, in the right order, every year.
Expat & Emigration Tax

Arrivals, departures and every residency question in between.

The move year is its own project: the elections and valuations filed that year decide the next decade of both countries’ returns.
Non-Resident Canadian Tax

Canadian income of non-residents — withholding fixed, refunds recovered.

Default withholding is 25% of gross: elective returns routinely turn over-withheld rent and pensions into refunds.
Transfer Pricing & BEPS

Arm’s-length pricing that is documented before anyone asks.

Documentation prepared with the return is the cheapest insurance in international tax; reconstructing it during an audit is the most expensive.
Tax Treaties & Withholding

DTAA relief, rate reductions and recoveries under Canada’s treaty network.

Relief is only as good as the paperwork claiming it — we build treaty positions that survive review on both sides.
Cross-Border Estates & Trusts

Two tax systems meeting at the hardest possible moment — planned in advance.

Wills drafted for one country routinely misfire in the other — deemed disposition here, estate tax there, credits in between.
Global Investments & Reporting

Foreign portfolios kept compliant — and located where tax treats them best.

Information returns carry the sharpest penalties — $25 a day whether or not any tax is owing. We keep them clean and on time.
Cross-Border Corporate Tax

Structure, expansion and repatriation for companies operating internationally.

Expansion raises the same four questions every time — entity, PE, repatriation, payroll. We answer them before the tax authorities do.
India Tax for NRIs & Returning Residents

Residency, TDS, repatriation and the DTAA, handled on both sides of the India file.

The deduction is taken on the sale price, not the gain — which is why an NRI property sale strands cash unless the certificate is applied for before closing.
Canadian Tax with a Foreign Element

Arriving, leaving, or living in Canada with income, property or accounts somewhere else.

Residency is decided on facts, not on a form — and the year you arrive or leave is the one where the largest amounts turn on the smallest details.
UAE Tax for Expats & Their Home Country

No personal income tax in the UAE does not settle what the country you left still expects.

A zero-tax country is only half the answer — the question that decides the bill is whether the country you came from still treats you as resident.
We Work with Your Preferred Accounting Software
QuickBooks
Xero
Zoho Books
Wagepoint
Stripe
FreshBooks
Wave
Sage
ProFile
Excel Sheets
QuickBooks
Xero
Zoho Books
Wagepoint
Stripe
FreshBooks
Wave
Sage
ProFile
Excel Sheets

Industries & Client Types We Serve Worldwide

Global E-commerce & Marketplaces
Technology & SaaS
Professional Services Firms
Cross-Border Real Estate
Importers, Exporters & Manufacturers
Athletes, Artists & Entertainers
Remote Workers & Digital Nomads
Investment Funds & Holding Companies
Global E-commerce & Marketplaces

Cross-border tax for sellers shipping worldwide: marketplace withholding, foreign registrations and inventory nexus handled before they become audits.

Marketplaces withhold, remit and report in their own right, so the tax position of a single sale is decided by where the stock sat, where the buyer was and which platform collected — not by where the company is registered. We reconcile the platform's own filings against the returns before either is submitted.

  • Foreign VAT / GST / sales tax registrations
  • Marketplace withholding reviews
  • Inventory nexus & PE analysis
  • Multi-currency books reconciled
Explore E-commerce & Marketplaces
Technology & SaaS

Software revenue crosses borders by default — sourcing rules, withholding on licence-like payments and IP location decide the effective rate.

Software revenue is rarely taxed where the team sits. Licence, subscription and service income are characterised differently by each side, and the answer decides withholding at source, treaty relief and whether a foreign customer creates a taxable presence at all — questions that are cheap to settle before the contract and expensive afterwards.

  • Cross-border revenue sourcing & withholding
  • IP structuring with real substance
  • Equity for cross-border teams
  • U.S. expansion: entity & PE setup
Explore Technology & SaaS
Professional Services Firms

Firms and partners working across borders meet Regulation 105 withholding, PE risk on long engagements and per-country payroll for travelling staff.

A partnership is taxed in the hands of its partners, so one engagement abroad can reach every partner's personal return. The order matters: the waiver is applied for before the invoice, the presence is tracked before it becomes an establishment, and the payroll is registered before the first day worked in the other country.

  • Reg 105 / 102 waivers
  • Permanent establishment risk
  • Partner mobility planning
  • Cross-border withholding recovery
Explore Professional Services
Cross-Border Real Estate

Foreign property income and sales are taxed in both countries by default; Section 216, FIRPTA and treaty credits are the standing toolkit.

Property is taxed where it sits, which is the one rule no treaty overrides. What the treaty does decide is the credit, the rate on the rent and what happens on the sale — and the clearance certificate on a disposition is applied for before closing, not after the buyer has already held the money back.

  • Section 216 rental returns
  • FIRPTA withholding recovery
  • Section 116 clearance
  • Treaty credit optimization
Explore Real Estate
Importers, Exporters & Manufacturers

Related-party purchasing, customs value versus transfer price, and foreign-affiliate structures put trading businesses inside the s.247 documentation rules.

Goods crossing a border move the tax question from income to indirect: registration thresholds, place of supply, the customs value and the transfer price between related entities all have to agree with each other. When they do not, the adjustment arrives from two authorities at once and each one uses the other's number.

  • Transfer pricing documentation (s.247)
  • Customs value vs transfer price
  • Foreign affiliate reporting (T1134)
  • Country-by-country reporting
Explore Trade & Manufacturing
Athletes, Artists & Entertainers

Performance income is taxed where earned — Regulation 105 in Canada, withholding agreements in the U.S. — with special treaty articles overriding the usual rules.

Performance income is taxed where the performance happens, and the deduction is usually taken at source on the gross fee before expenses. Recovering the difference is a filing exercise in the other country, and it only works if the tour, the residency and the withholding certificates were documented while the work was being done.

  • Reg 105 & U.S. CWA agreements
  • Multi-state & country calendars
  • Touring income allocation
  • Royalty & image-rights withholding
Explore Athletes & Entertainers
Remote Workers & Digital Nomads

Working from anywhere doesn't mean taxed nowhere: residency defaults, employer payroll exposure and treaty relief decide where income actually lands.

Working from another country does not by itself end tax residence in the one you left, and it can start one where you are sitting. Day counts, ties, the employer's own exposure and the treaty tie-breaker all point at the same question, and the year you move is the year it has to be answered on paper.

  • Residency analysis before moving
  • Employer payroll exposure
  • Totalization & social security
  • Foreign tax credits
Explore Remote Workers
Investment Funds & Holding Companies

Holding structures live or die on treaty access, beneficial ownership and substance — the MLI's principal-purpose test now sits over every arrangement.

A holding structure is only as good as its reporting. Foreign affiliates, accrued passive income and distributions each carry their own return, and the penalties on those attach to the form rather than to any tax being owed — so a structure that saves tax can still cost money if the information returns are late.

  • Treaty access & PPT reviews
  • FAPI & surplus computations
  • Withholding-efficient routing
  • Governance & substance
Explore Funds & Holdcos

Our Expert Punjab Accounting Firm & Accounting Team

Udit Gupta, International tax, cross-border tax and transfer pricing: USA, Canada, India and UAE at LQ Consultants
Director · International Tax, Cross-Border Tax & Transfer Pricing Expert

CA (India), CA (Malaysia)

Udit Gupta on LinkedIn

Abhinav Gupta, India international tax, cross-border tax and transfer pricing at LQ Consultants
Director · India International Tax, Cross-Border Tax & Transfer Pricing

CA (India)

Abhinav Gupta on LinkedIn

Raghav Gupta, UAE and India international tax, cross-border tax and transfer pricing at LQ Consultants
Director · UAE & India International Tax, Cross-Border Tax & Transfer Pricing

FCA (India)

Raghav Gupta on LinkedIn

Anmol Mittal, USA and Canada international tax, cross-border tax and transfer pricing at LQ Consultants
Director · USA & Canada International Tax, Cross-Border Tax & Transfer Pricing

CPA (Canada), CPA (USA), CA (India)

Anmol Mittal on LinkedIn

Vinayak Indolia, CFO services for Canada and India at LQ Consultants
Director · CFO Services, Canada & India

CPA (Canada), CA (India)

Vinayak Indolia on LinkedIn

Meet Our Entire Team of Experts

Other Local Office Locations in India

We serve businesses and individuals cross-province. Connect with our experts near you.

Maharashtra Office Delhi Office Karnataka Office Gujarat Office Telangana Office

Punjab Frequently Asked Questions

How much does a tax accountant in Punjab cost?

A corporate cross-border filing starts at $999 and an individual cross-border return at $349, the same fixed fees in every country we work in. Punjab clients pay no location premium, and the number is agreed in writing before work starts. See the full pricing breakdown.

Do I need to meet my Punjab accountant in person?

That is your choice. We have offices in India, the USA, Canada and the UAE, and you are welcome at any of them. Where a visit is not convenient, documents are exchanged on secure cloud software and signed electronically, so nothing travels by mail and nothing is lost in transit. Either way, the same practitioner prepares and reviews the file.

Which tax deadlines apply to Punjab businesses?

Corporate T2 returns are due six months after your fiscal year-end, with any balance owing payable within two or three months depending on your CCPC status. Personal T1 returns are due April 30, and June 15 for the self-employed. GST/HST depends on your filing frequency.

Can you handle both my corporate and personal returns?

Yes, and doing both together is where most of the planning value sits. Salary-versus-dividend mix, shareholder loans and RRSP room interact across the two returns, and treating them separately is how owners overpay. Explore all our services.

What if my books are behind by several years?

That is routine work for us. We rebuild the ledger year by year, file the outstanding returns in sequence, and where eligible apply to the CRA's Voluntary Disclosures Program to reduce penalties and interest.

Are you accepting new Punjab clients?

Yes, we are actively taking on new corporate and personal clients in Punjab, including mid-season transfers from another accountant. Transferring is straightforward and we request the prior files on your behalf.

What industries do you serve in Punjab?

Construction, healthcare and medical practices, restaurants, e-commerce, real estate, transportation, professional services, technology startups and registered non-profits. Each carries a distinct deduction profile. See our industry specialisms.

How do I switch to your firm from my current accountant?

Tell us who currently holds your files and we handle the professional handover, including requesting working papers and prior-year returns. There is no gap in your compliance and no awkward conversation required on your side.

What is the Canadian corporate filing deadline for clients in Punjab?

For clients in Punjab who file in Canada, the T2 is due within six months of the corporation's fiscal year-end (CRA, 2025). If Canadian tax is owing, the balance is due within 2 or 3 months of the year-end. Punjab sets its own deadlines for any local return, and we work to those separately.

How much do you charge for tax work in Punjab?

Every engagement is quoted as a fixed fee in writing before any work starts. The quote depends on the filings your position actually needs rather than on time spent, so you know the number in advance.

Does your firm handle CRA audits and reviews for clients in Punjab?

Yes. We respond to CRA queries, reviews and audits on your behalf, including the residency and foreign-reporting questions that most often arise for clients with income or assets in more than one country.

Do you have an office in Punjab?

Our Canadian office is at 381 Front St W, Toronto ON, and we have offices in India, the USA and the UAE. Clients in Punjab are welcome at any of them; where a visit is not convenient, documents are exchanged on secure cloud software and signed electronically. Call +1-416-619-0068 to talk it through.

Which countries have a tax treaty with the United States?

Around sixty, including Canada, the United Kingdom, India, Australia and most of western Europe — but the list matters less than the terms, because each treaty caps rates and allocates income differently. Two countries with treaties can produce opposite answers on the same pension or the same royalty. What decides your position is the specific article covering your income type. See our country guides.

Do I have to file in both countries?

Frequently yes, and the two filings do different jobs. The country where the income arises taxes it at source; the country where you are resident taxes your worldwide income and then gives credit for the tax already paid. Filing only one side is what leaves relief unclaimed — the credit has to be asked for on a return. We prepare both sides so the numbers agree. See dual filing.

Still have questions? View our FAQ page or contact us.

24-Hour Helpline: +1 (416) 619-0068

Ready to get started with Punjab?

Talk to a professional tax accountant about your situation. No obligation, and the fee is agreed in writing before any work starts.

  • Tax accountant led team
  • Fixed fees, no hourly billing
  • 18,000+ clients served

Files that look like this one

Case study 1

From student visa to permanent residence with accounts left in Punjab

The client arrived as a student, later became a permanent resident, and had filed straightforward returns throughout without reporting interest on the deposits held in her name in Punjab. We fixed the date residence began from the facts of her arrival and her ties, established which years remained open, and worked out which accounts were genuinely hers rather than her parents' with her name added. The engagement produced amended returns reporting the Indian interest, foreign property disclosures for the years the threshold was met, and a written record of the residence determination for the file.

Case study 2

Sale of inherited farmland in Punjab by a Canadian resident

A client inherited a share of family land and sold it some years after emigrating. No Indian tax arose on the sale, and he assumed that ended the matter. We established the value at which the land came to him from the succession documents, converted it at the rate applying then, and computed the Canadian gain on that basis. The engagement produced a Canadian return reporting the disposition with the valuation and conversion working attached, and a written note explaining why no foreign tax credit was available to set against it.

Case study 3

Documenting a family transfer from Punjab after a bank query

A transfer from a parent's account in Punjab towards a house purchase drew a query, and the client had nothing beyond the wire confirmation. We worked back through the Indian bank records, obtained written confirmation of the gift and of the relationship, and set out the source of the funds in the parent's own hands. The engagement produced a documented response establishing that the receipt was a gift and not income, together with a separate correction for interest the client's own Indian account had earned, which the review had also brought to the surface.

Case study 4

Retiring to Punjab with pension income arising in Canada

The client returned to Punjab after a working life in Canada and found tax withheld on the gross amount of every pension payment, with no return to file and no way to use his credits. We compared the withholding against what the same income would bear if taxed as a resident, made the election available for that pension income, and filed for the year. The engagement produced a return under the election, a refund of the excess withheld, and a written schedule he can follow each year, since the election must be made annually and on time.

Case study 5

Rental property in Canada owned by a family living in Punjab

The family had returned to Punjab and kept a house in Canada let to tenants, with the managing agent remitting nothing to the tax authority. Rent paid to a non-resident is withheld on the gross amount unless an election is made to be taxed on the net rent instead. We regularised the account, made the election, and filed the outstanding non-resident returns with expenses properly supported. The engagement produced a compliant withholding arrangement going forward, filed returns for the years in arrears, and a recovery of withholding that exceeded the tax actually due.

Case study 6

Joint accounts held with parents in Punjab and who reports them

A client had been named on several accounts in Punjab so that his parents could operate them, and he had been reporting all of the interest on his Canadian return. We traced the source of the funds in each account and the pattern of use, and established which balances were genuinely his and which were his parents' with his name added for convenience. The engagement produced corrected returns for the open years, a revised foreign property disclosure reflecting only his own holdings, and a written analysis supporting the split if it is ever questioned.

Case study 7

The Two-Year Window After Returning to India

Returning residents pass through a transitional status in which foreign income is largely outside the Indian net. The engagement establishes when the window opens and closes, and puts the transactions that benefit inside it.

Read how this one runs
Case study 8

A US Citizen Settled in India, Filing on Both Sides

Residence in India and citizenship in the United States produce two annual returns for one income. The order decides the credit, and the Indian financial year and the US calendar year have to be reconciled before either is prepared.

Read how this one runs

All case studies — every published engagement in one place.

Our practitioners are alumni of leading accounting and tax institutions

Where our partners studied — CPA Canada (In-Depth Tax Program), AICPA, the Institute of Chartered Accountants of India and the Malaysian Institute of Accountants.

Request a Quote +1 (416) 619-0068








