Cross-Border Tax Accountants in Hesse — low-cost, fixed fee

Fixed fees agreed before work starts – 18,000+ clients served

We plan and file cross-border taxes for individuals, corporations and trusts in Hesse — U.S. and Canadian returns, expat and non-resident filings, treaty relief and foreign reporting, at fixed fees agreed in writing. Ask us about low-cost Cross-Border Tax Accountants in Hesse: call the 24-hour helpline on +1 (416) 619-0068, or request a written fixed quote today.

Fixed-Fee · Trusted · Accurate · Quick · Easy · Economical

In-Depth Tax Trained
CPA Canada (In-Depth Tax Program)
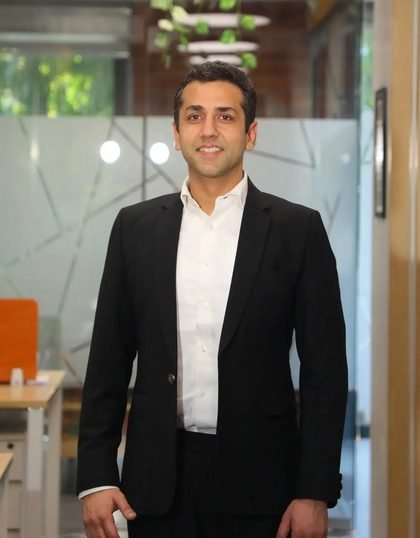
Udit Gupta, founder of Legal Quotient Consultants, at the firm's office
Udit Gupta Cross-Border Tax

Fixed Fees for Clients in Hesse

These are our own fixed fees, in US dollars, for the cross-border work we do for you — agreed in writing before work starts. They are not a price for filing under Hesse's own tax system, and they do not change with where you live.

See the full fee list

Cross-border and international tax for Hesse, Germany: Legal Quotient Consultants serves clients in Hesse remotely from Toronto — international tax planning, expat and non-resident filings, U.S. and Canadian returns, transfer pricing and treaty relief, at fixed fees.

How Hesse Filing Works

  1. 1
    Share

    Send your documents securely through our portal or by email.

  2. 2
    Prepare

    We prepare your hesse return and every supporting schedule.

  3. 3
    Review

    You review each figure and approve before anything is filed.

  4. 4
    File & pay

    We file with the tax authority the return belongs to and send you the confirmation of receipt.

Hesse: Legal Quotient Consultants vs. a Typical Firm

Factor Legal Quotient Consultants Typical Firm
Pricing model Fixed, flat fee Hourly / unpredictable
Experience 15+ years, 18,000+ clients Varies
Helpline 24 hours a day, +1 (416) 619-0068 Office hours only
Where we work Our offices in India, the USA, Canada and the UAE One office only
CRA audit support Included Billed extra

Key Canadian Tax Terms for Clients in Hesse

T1135
The foreign income verification statement Canadian residents file once specified foreign property passes $100,000 of cost at any time in the year (CRA, 2025 tax year).
Tax Treaty
The bilateral agreement that allocates taxing rights between two countries and relieves double taxation.
Withholding Tax
Tax deducted at source on cross-border payments — Canada's 25% Part XIII rate is often reduced by treaty.
Hesse: Our Analysis

German-source pensions paid to Canadian residents and posted-worker payroll are the recurring themes under the Canada–Germany treaty.

For clients in Hesse, engagements run through a secure portal with scheduled video reviews — the same specialist team and the same fixed fee wherever you are. Typical files pair local income and assets with Canadian filings or vice versa, sequenced so treaty relief and foreign tax credits are claimed once and correctly.

Cross-border tax in Hesse: what is different here

Hesse applies federal income tax, solidarity surcharge and church tax, sets its own real estate transfer tax rate at the higher end of the German range, and hosts in Frankfurt the country's financial centre and the European Central Bank. Frankfurt's banks, asset managers and the exchange bring transferred staff from Toronto, New York, London and Mumbai, and with them deferred compensation, carried interest and bonus deferrals that two systems tax at different moments.

The recurring questions are German unlimited liability from the arrival date, the treatment of Canadian and American retirement accounts under German law, bonuses earned in one country and paid in another, and — for the many who arrive on a fixed-term posting — the split-year rules and the employer's obligation to run German payroll withholding from day one.

  • Frankfurt banking and asset-management transferees from Toronto, New York and London with deferred compensation and home-country pensions.
  • International-organisation staff and their families with special status and the residency questions of a spouse who works locally.
  • Indian financial-sector professionals with Indian investments and property reported under the Germany–India treaty.

My bonus was earned in Toronto but paid after I moved to Frankfurt. Who taxes it? Both may claim it: Canada as employment income sourced to work performed there, Germany as income received by a resident. The treaty allocates it to where the work was done, and the other side gives credit or exemption.

Is Hesse's property transfer tax higher than elsewhere in Germany? Each Land sets its own rate and Hesse's sits toward the upper end; the current rate is confirmed for any Frankfurt purchase before the notary appointment.

Why Choose Legal Quotient Consultants in Hesse?

Expert Hesse Tax Filing & Planning

Providing tailored Hesse tax filing and planning to reduce liabilities, maximize refunds, and ensure compliance in every jurisdiction that taxes the file.

Fixed Fees, Agreed Before We Start

Hesse filing quoted as a fixed fee before work begins, with no hidden extras — the number you are quoted is the number you are billed.

Compliance & Cross Border Tax

From information returns to corporate audits, protect your Hesse business with compliance in every jurisdiction that taxes the file and expert cross border tax strategies.

A Secure Engagement

Documents, questions and signatures move through one secure portal, so a Hesse file runs the same from Toronto, Dubai or Delhi.

Two of the firm’s advisers at the glass desk in the Delhi office
Secure Fixed Quote

Fill details below to lock in pricing and get started today.

"A Unique Hesse Approach – Fixed Fee First, Reviewed Before Filing!"

  • Step 1: Share your information – we scope the work on the first call.
  • Step 2: Fixed fee quoted in writing before any work starts.
  • Step 3: We prepare your financials & tax return.
  • Step 4: Review & sign the deliverable before anything is filed.
  • Step 5: We file your return & share final documents.
  • Step 6: The fee was agreed before we started – nothing changes at the end.

Quoted up front, in writing.

Contact Us

Core International & Cross-Border Tax Services

International Tax Planning & Advisory

Strategy and compliance for income, assets and families spread across borders.

One coordinating team: filings on every side of the border are sequenced so treaty relief and foreign tax credits are claimed once — and in the right country.
U.S. & Cross-Border Tax Returns

Both systems, one desk — 1040s and T1s planned together, not in isolation.

Dual filers: U.S. citizens in Canada and Canadians with U.S. income run two parallel systems — we prepare both, in the right order, every year.
Expat & Emigration Tax

Arrivals, departures and every residency question in between.

The move year is its own project: the elections and valuations filed that year decide the next decade of both countries’ returns.
Non-Resident Canadian Tax

Canadian income of non-residents — withholding fixed, refunds recovered.

Default withholding is 25% of gross: elective returns routinely turn over-withheld rent and pensions into refunds.
Transfer Pricing & BEPS

Arm’s-length pricing that is documented before anyone asks.

Documentation prepared with the return is the cheapest insurance in international tax; reconstructing it during an audit is the most expensive.
Tax Treaties & Withholding

DTAA relief, rate reductions and recoveries under Canada’s treaty network.

Relief is only as good as the paperwork claiming it — we build treaty positions that survive review on both sides.
Cross-Border Estates & Trusts

Two tax systems meeting at the hardest possible moment — planned in advance.

Wills drafted for one country routinely misfire in the other — deemed disposition here, estate tax there, credits in between.
Global Investments & Reporting

Foreign portfolios kept compliant — and located where tax treats them best.

Information returns carry the sharpest penalties — $25 a day whether or not any tax is owing. We keep them clean and on time.
Cross-Border Corporate Tax

Structure, expansion and repatriation for companies operating internationally.

Expansion raises the same four questions every time — entity, PE, repatriation, payroll. We answer them before the tax authorities do.
India Tax for NRIs & Returning Residents

Residency, TDS, repatriation and the DTAA, handled on both sides of the India file.

The deduction is taken on the sale price, not the gain — which is why an NRI property sale strands cash unless the certificate is applied for before closing.
Canadian Tax with a Foreign Element

Arriving, leaving, or living in Canada with income, property or accounts somewhere else.

Residency is decided on facts, not on a form — and the year you arrive or leave is the one where the largest amounts turn on the smallest details.
UAE Tax for Expats & Their Home Country

No personal income tax in the UAE does not settle what the country you left still expects.

A zero-tax country is only half the answer — the question that decides the bill is whether the country you came from still treats you as resident.
We Work with Your Preferred Accounting Software
QuickBooks
Xero
Zoho Books
Wagepoint
Stripe
FreshBooks
Wave
Sage
ProFile
Excel Sheets
QuickBooks
Xero
Zoho Books
Wagepoint
Stripe
FreshBooks
Wave
Sage
ProFile
Excel Sheets

Industries & Client Types We Serve Worldwide

Global E-commerce & Marketplaces
Technology & SaaS
Professional Services Firms
Cross-Border Real Estate
Importers, Exporters & Manufacturers
Athletes, Artists & Entertainers
Remote Workers & Digital Nomads
Investment Funds & Holding Companies
Global E-commerce & Marketplaces

Cross-border tax for sellers shipping worldwide: marketplace withholding, foreign registrations and inventory nexus handled before they become audits.

Marketplaces withhold, remit and report in their own right, so the tax position of a single sale is decided by where the stock sat, where the buyer was and which platform collected — not by where the company is registered. We reconcile the platform's own filings against the returns before either is submitted.

  • Foreign VAT / GST / sales tax registrations
  • Marketplace withholding reviews
  • Inventory nexus & PE analysis
  • Multi-currency books reconciled
Explore E-commerce & Marketplaces
Technology & SaaS

Software revenue crosses borders by default — sourcing rules, withholding on licence-like payments and IP location decide the effective rate.

Software revenue is rarely taxed where the team sits. Licence, subscription and service income are characterised differently by each side, and the answer decides withholding at source, treaty relief and whether a foreign customer creates a taxable presence at all — questions that are cheap to settle before the contract and expensive afterwards.

  • Cross-border revenue sourcing & withholding
  • IP structuring with real substance
  • Equity for cross-border teams
  • U.S. expansion: entity & PE setup
Explore Technology & SaaS
Professional Services Firms

Firms and partners working across borders meet Regulation 105 withholding, PE risk on long engagements and per-country payroll for travelling staff.

A partnership is taxed in the hands of its partners, so one engagement abroad can reach every partner's personal return. The order matters: the waiver is applied for before the invoice, the presence is tracked before it becomes an establishment, and the payroll is registered before the first day worked in the other country.

  • Reg 105 / 102 waivers
  • Permanent establishment risk
  • Partner mobility planning
  • Cross-border withholding recovery
Explore Professional Services
Cross-Border Real Estate

Foreign property income and sales are taxed in both countries by default; Section 216, FIRPTA and treaty credits are the standing toolkit.

Property is taxed where it sits, which is the one rule no treaty overrides. What the treaty does decide is the credit, the rate on the rent and what happens on the sale — and the clearance certificate on a disposition is applied for before closing, not after the buyer has already held the money back.

  • Section 216 rental returns
  • FIRPTA withholding recovery
  • Section 116 clearance
  • Treaty credit optimization
Explore Real Estate
Importers, Exporters & Manufacturers

Related-party purchasing, customs value versus transfer price, and foreign-affiliate structures put trading businesses inside the s.247 documentation rules.

Goods crossing a border move the tax question from income to indirect: registration thresholds, place of supply, the customs value and the transfer price between related entities all have to agree with each other. When they do not, the adjustment arrives from two authorities at once and each one uses the other's number.

  • Transfer pricing documentation (s.247)
  • Customs value vs transfer price
  • Foreign affiliate reporting (T1134)
  • Country-by-country reporting
Explore Trade & Manufacturing
Athletes, Artists & Entertainers

Performance income is taxed where earned — Regulation 105 in Canada, withholding agreements in the U.S. — with special treaty articles overriding the usual rules.

Performance income is taxed where the performance happens, and the deduction is usually taken at source on the gross fee before expenses. Recovering the difference is a filing exercise in the other country, and it only works if the tour, the residency and the withholding certificates were documented while the work was being done.

  • Reg 105 & U.S. CWA agreements
  • Multi-state & country calendars
  • Touring income allocation
  • Royalty & image-rights withholding
Explore Athletes & Entertainers
Remote Workers & Digital Nomads

Working from anywhere doesn't mean taxed nowhere: residency defaults, employer payroll exposure and treaty relief decide where income actually lands.

Working from another country does not by itself end tax residence in the one you left, and it can start one where you are sitting. Day counts, ties, the employer's own exposure and the treaty tie-breaker all point at the same question, and the year you move is the year it has to be answered on paper.

  • Residency analysis before moving
  • Employer payroll exposure
  • Totalization & social security
  • Foreign tax credits
Explore Remote Workers
Investment Funds & Holding Companies

Holding structures live or die on treaty access, beneficial ownership and substance — the MLI's principal-purpose test now sits over every arrangement.

A holding structure is only as good as its reporting. Foreign affiliates, accrued passive income and distributions each carry their own return, and the penalties on those attach to the form rather than to any tax being owed — so a structure that saves tax can still cost money if the information returns are late.

  • Treaty access & PPT reviews
  • FAPI & surplus computations
  • Withholding-efficient routing
  • Governance & substance
Explore Funds & Holdcos

Our Expert Hesse Accounting Firm & Accounting Team

Udit Gupta, International tax, cross-border tax and transfer pricing: USA, Canada, India and UAE at LQ Consultants
Director · International Tax, Cross-Border Tax & Transfer Pricing Expert

CA (India), CA (Malaysia)

Udit Gupta on LinkedIn

Abhinav Gupta, India international tax, cross-border tax and transfer pricing at LQ Consultants
Director · India International Tax, Cross-Border Tax & Transfer Pricing

CA (India)

Abhinav Gupta on LinkedIn

Raghav Gupta, UAE and India international tax, cross-border tax and transfer pricing at LQ Consultants
Director · UAE & India International Tax, Cross-Border Tax & Transfer Pricing

FCA (India)

Raghav Gupta on LinkedIn

Anmol Mittal, USA and Canada international tax, cross-border tax and transfer pricing at LQ Consultants
Director · USA & Canada International Tax, Cross-Border Tax & Transfer Pricing

CPA (Canada), CPA (USA), CA (India)

Anmol Mittal on LinkedIn

Vinayak Indolia, CFO services for Canada and India at LQ Consultants
Director · CFO Services, Canada & India

CPA (Canada), CA (India)

Vinayak Indolia on LinkedIn

Meet Our Entire Team of Experts

Other Local Office Locations in Germany

We serve businesses and individuals cross-province. Connect with our experts near you.

Bavaria Office Berlin Office North Rhine-Westphalia Office

Hesse Frequently Asked Questions

How much does a tax accountant in Hesse cost?

A corporate cross-border filing starts at $999 and an individual cross-border return at $349, the same fixed fees in every country we work in. Hesse clients pay no location premium, and the number is agreed in writing before work starts. See the full pricing breakdown.

Do I need to meet my Hesse accountant in person?

That is your choice. We have offices in India, the USA, Canada and the UAE, and you are welcome at any of them. Where a visit is not convenient, documents are exchanged on secure cloud software and signed electronically, so nothing travels by mail and nothing is lost in transit. Either way, the same practitioner prepares and reviews the file.

Which tax deadlines apply to Hesse businesses?

Corporate T2 returns are due six months after your fiscal year-end, with any balance owing payable within two or three months depending on your CCPC status. Personal T1 returns are due April 30, and June 15 for the self-employed. GST/HST depends on your filing frequency.

Can you handle both my corporate and personal returns?

Yes, and doing both together is where most of the planning value sits. Salary-versus-dividend mix, shareholder loans and RRSP room interact across the two returns, and treating them separately is how owners overpay. Explore all our services.

What if my books are behind by several years?

That is routine work for us. We rebuild the ledger year by year, file the outstanding returns in sequence, and where eligible apply to the CRA's Voluntary Disclosures Program to reduce penalties and interest.

Are you accepting new Hesse clients?

Yes, we are actively taking on new corporate and personal clients in Hesse, including mid-season transfers from another accountant. Transferring is straightforward and we request the prior files on your behalf.

What industries do you serve in Hesse?

Construction, healthcare and medical practices, restaurants, e-commerce, real estate, transportation, professional services, technology startups and registered non-profits. Each carries a distinct deduction profile. See our industry specialisms.

How do I switch to your firm from my current accountant?

Tell us who currently holds your files and we handle the professional handover, including requesting working papers and prior-year returns. There is no gap in your compliance and no awkward conversation required on your side.

What is the Canadian corporate filing deadline for clients in Hesse?

For clients in Hesse who file in Canada, the T2 is due within six months of the corporation's fiscal year-end (CRA, 2025). If Canadian tax is owing, the balance is due within 2 or 3 months of the year-end. Hesse sets its own deadlines for any local return, and we work to those separately.

How much do you charge for tax work in Hesse?

Every engagement is quoted as a fixed fee in writing before any work starts. The quote depends on the filings your position actually needs rather than on time spent, so you know the number in advance.

Does your firm handle CRA audits and reviews for clients in Hesse?

Yes. We respond to CRA queries, reviews and audits on your behalf, including the residency and foreign-reporting questions that most often arise for clients with income or assets in more than one country.

Do you have an office in Hesse?

Our Canadian office is at 381 Front St W, Toronto ON, and we have offices in India, the USA and the UAE. Clients in Hesse are welcome at any of them; where a visit is not convenient, documents are exchanged on secure cloud software and signed electronically. Call +1-416-619-0068 to talk it through.

What happens if I have not filed for several years?

Missed years are handled as one package, not one at a time, because the route chosen for the first year determines the relief available for the rest. Each country has a disclosure or relief programme with its own conditions, and entering the right one — before the authority contacts you — is usually what keeps penalties down. Filing quietly outside a programme forfeits that protection. See catching up on missed returns.

Do I pay tax when I inherit property abroad?

The inheritance itself is often not income to you, but three other things can create tax: the estate may owe tax where the deceased or the property was situated, some countries tax the recipient directly, and the gain from the date you inherit to the date you sell is yours. Reporting obligations can also attach to holding the asset. See inheriting property abroad.

Still have questions? View our FAQ page or contact us.

24-Hour Helpline: +1 (416) 619-0068

Ready to get started with Hesse?

Talk to a professional tax accountant about your situation. No obligation, and the fee is agreed in writing before any work starts.

  • Tax accountant led team
  • Fixed fees, no hourly billing
  • 18,000+ clients served

Cross-border situations we are engaged for

Case study 1

Reconciling a tax equalisation settlement for a Frankfurt secondee

A banking secondee in Frankfurt was presented with an equalisation settlement showing a large amount owed back to the employer, calculated by a provider who had never seen her personal investment income. We rebuilt the calculation, established which items the policy actually covered and which were hers alone, and identified where the hypothetical tax had been computed on assumptions that no longer matched the filed returns. The employer accepted a revised settlement. The engagement produced a reconciled calculation, returns in both countries that agree with each other, and a note for the following year’s policy.

Case study 2

Sourcing a bonus paid after a move from Canada to Hesse

A client received a performance bonus months after taking up a post in Hesse, and the Canadian payer withheld nothing on the view that she was no longer employed there. The plan document showed the award related to a performance period worked entirely in Canada. We apportioned the payment by workdays, reported the Canadian source portion on a non-resident basis, and set out the credit position for the German adviser. The engagement produced a filed Canadian return, a written sourcing analysis supported by the plan document, and a correction to the payer’s treatment of later awards.

Case study 3

Building the foreign account reporting for an American in Frankfurt

A United States citizen working in Frankfurt had filed returns for years without any of the foreign account reporting that accompanies them, and held several German investment and pension wrappers nobody had examined. We inventoried every account and holding, applied each reporting test separately rather than assuming that one list served both, and looked at the wrappers individually, because domestic treatment does not decide the reporting question. The engagement produced the missing reports for the open years, a filed position on each wrapper, and an annual schedule the client now maintains alongside the return.

Case study 4

Characterising distributions from a Canadian trust to a Hesse beneficiary

A beneficiary in Hesse received irregular payments from a family trust in Canada and had reported them inconsistently, sometimes as income and sometimes not at all. We obtained the trust accounts and the trustee’s designations, separated income distributions from capital, checked the withholding applied against the treaty category each payment fell into, and recovered where too much had been taken. The engagement produced a year by year characterisation of every payment, corrected filings, and a standing instruction to the trustee about the slips the beneficiary needs each year.

Case study 5

Testing withholding and interest deductions on a related party loan

A Canadian subsidiary had been funded largely by a loan from its German parent, with interest accruing and nobody testing either side of the arrangement. We established that the lender was not at arm’s length, so withholding applied to the interest at the treaty rate rather than not at all, and tested the debt against the equity the rules measure it by, which denied a deduction for part of the interest. The engagement produced corrected withholding remittances, a return filed with the restricted deduction, and a recapitalisation plan the parent adopted for the year after.

Case study 6

Choosing a basis for Canadian pension payments on retiring to Hesse

A client retiring to Hesse had several Canadian income streams and had been told simply to accept withholding at source on all of them. Some were eligible for an election to be taxed on the ordinary basis instead, and the total income was low enough for that to be worth testing. We calculated both outcomes, filed the election where it produced the better result, and gave the payers the residency evidence they needed to apply the treaty rate to the rest. The engagement produced a filed election, corrected withholding instructions, and a note of when it has to be revisited.

Case study 7

Three Account Types, Three Tax Answers

Interest on each is treated differently and the deduction at source follows the account rather than the person. Holding the wrong one for the purpose is a recurring and avoidable cost.

Read how this one runs
Case study 8

A US LLC Owned From Canada

The two countries classify the vehicle differently, so relief that ought to apply frequently does not and the same profit can be taxed in both hands. The engagement examines whether the structure can be changed and what the change itself costs.

Read how this one runs

All case studies — every published engagement in one place.

Our practitioners are alumni of leading accounting and tax institutions

Where our partners studied — CPA Canada (In-Depth Tax Program), AICPA, the Institute of Chartered Accountants of India and the Malaysian Institute of Accountants.

Request a Quote +1 (416) 619-0068








